The Swiss National Bank will conduct its final monetary policy assessment of the year in December. Inflation rose to 1.5% in October but remains within the SNB’s target range. We expect the SNB to keep its policy rate at 0.00% for now and to take a first step to 0.25% in March 2027 at the earliest. At the long end, September’s rise in rates did not continue in October: the yield on 10-year Swiss government bonds stood at around 0.50% at the end of October.
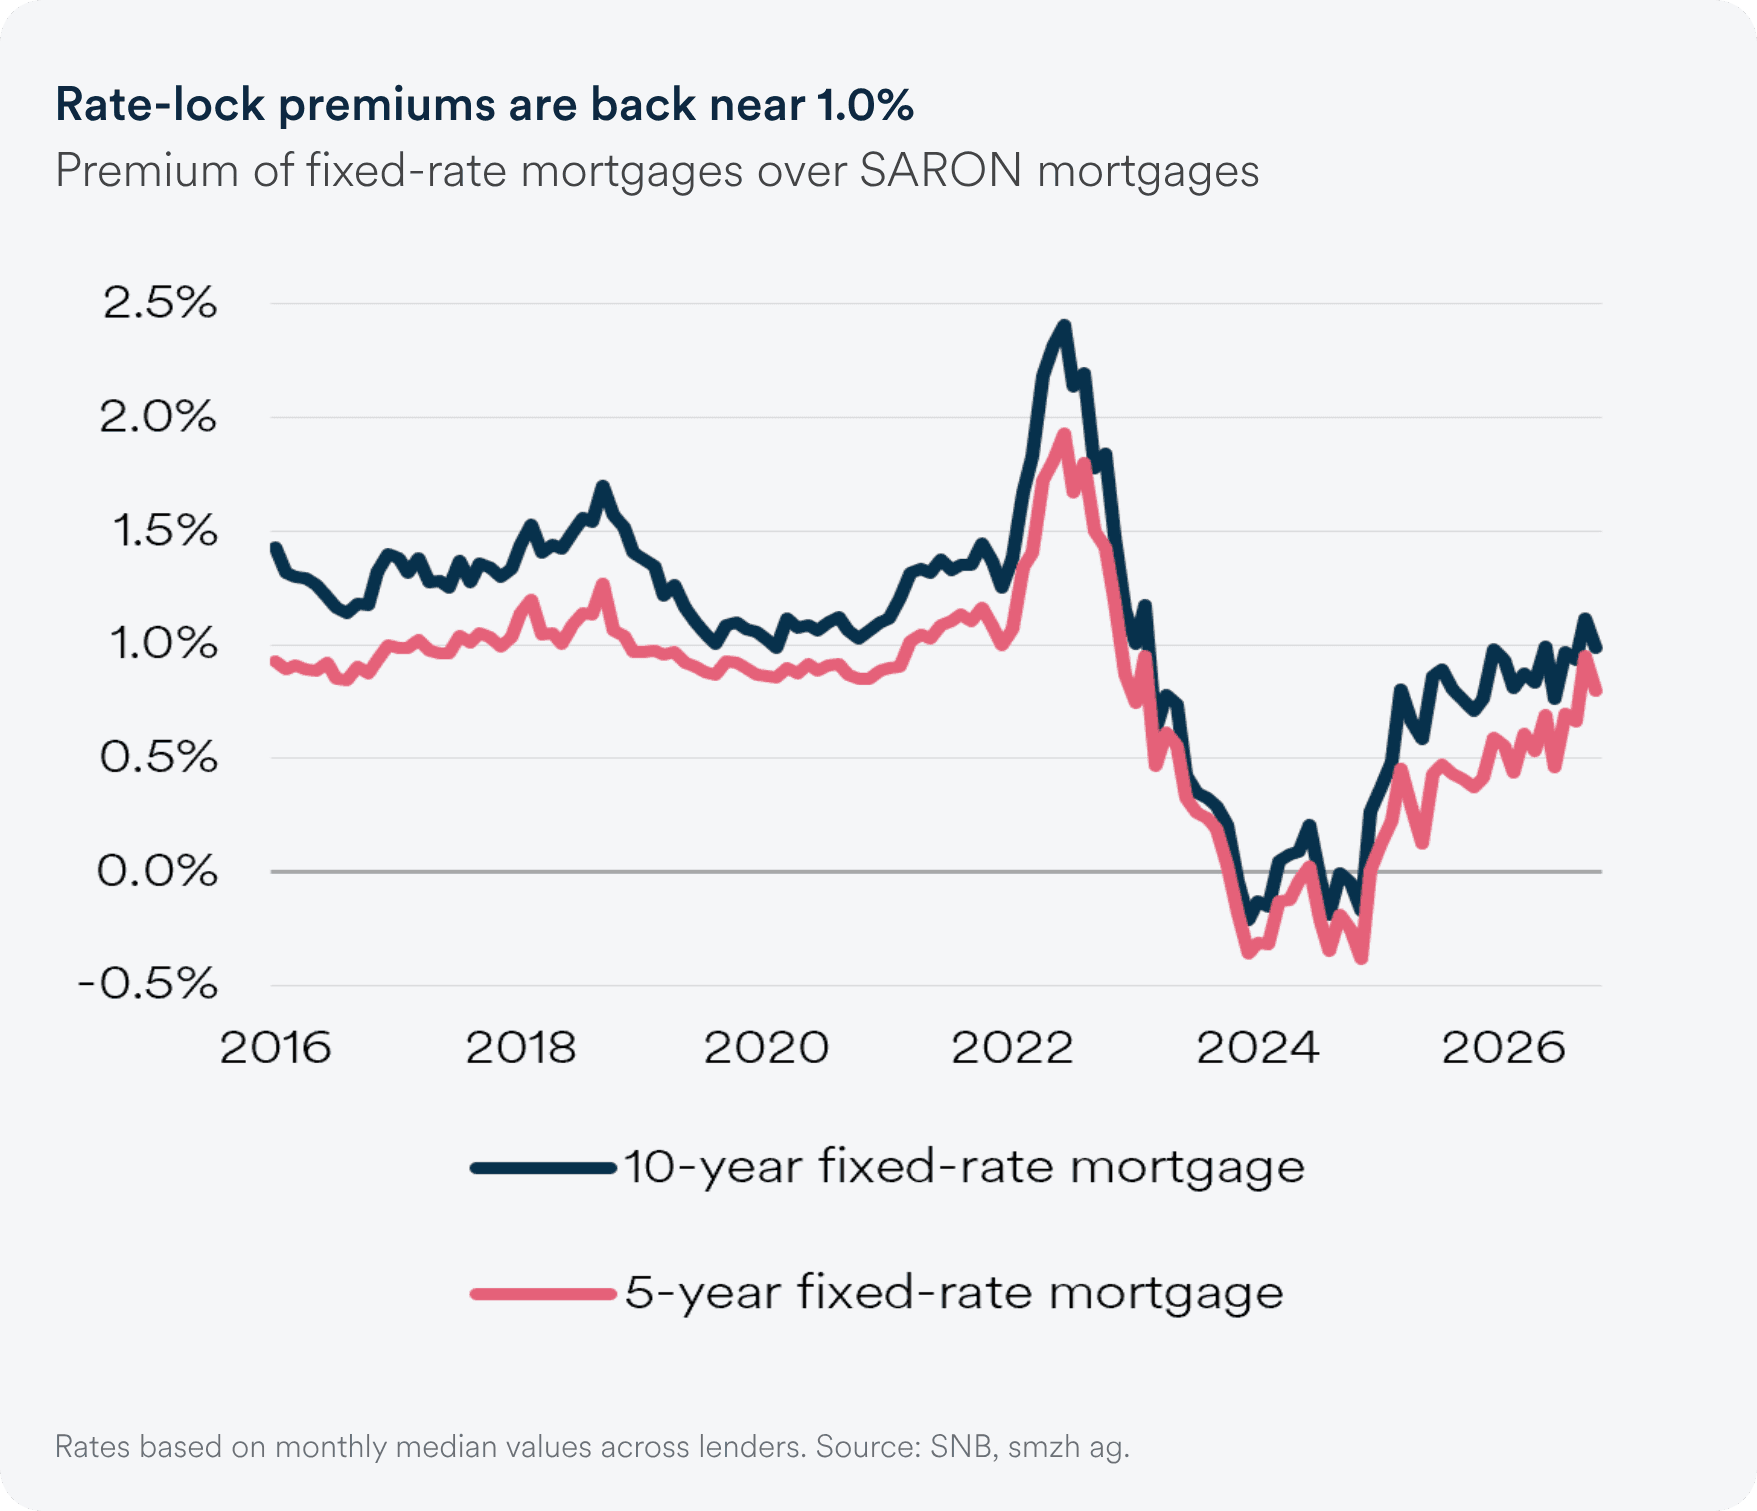
Fixed-rate mortgages are maintaining their higher level. Depending on the lender, 10-year terms currently range from around 1.65% to 2.10%, 5-year terms from 1.55% to 1.95%, and 2-year terms from 1.35% to 1.75%. At 0.85% to 1.15%, SARON mortgages remain the lowest-cost option. The premium for a 10-year fixed-rate mortgage over a SARON mortgage now stands at around one percentage point, close to pre-pandemic levels. On a mortgage of CHF 800,000, that means just under CHF 8'000 in additional costs per year. For the fixed-rate mortgage to pay off, short-term rates would need to average around 1.00% over the term. Since 2000, the policy rate has averaged around 0.5%